


What Is an Investment Actually For?
Ask most people what they want from their investments and the answer usually comes back quickly.
A good return.
That is understandable. Returns are easy to measure, easy to compare and endlessly discussed.
But I think it starts the investment conversation in the wrong place.
The more important question is:
What is the investment actually for?
That might sound obvious, but it changes almost everything.
An investment is rarely an end in itself.
It exists to help fund something.
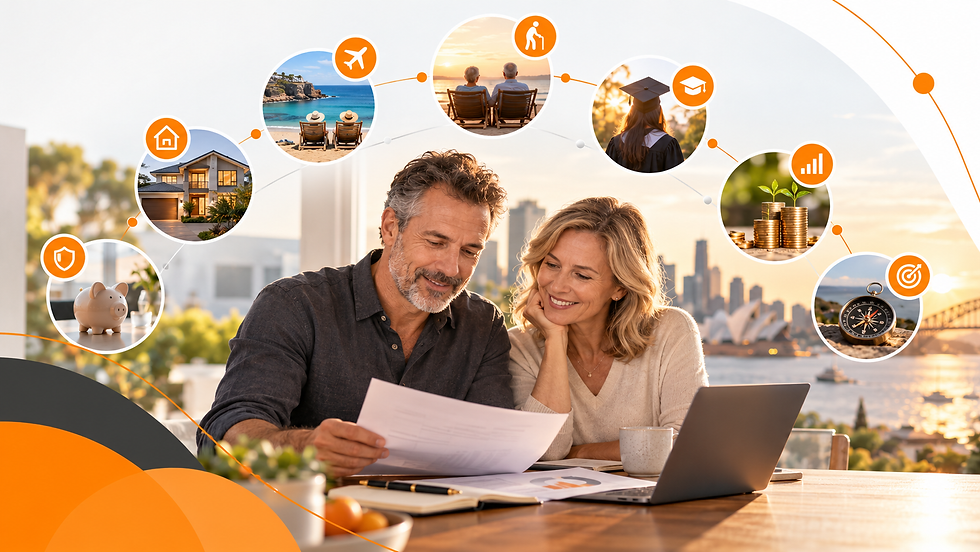
A retirement.
A home.
A child's education.
Travel.
Financial independence.
An income stream.
A safety margin.
An inheritance.
Or simply the confidence of knowing that money will be there when it is needed.
Once you start there, investing becomes less about chasing returns and more about solving a financial problem.
Start with the life, not the portfolio
Two people can have exactly the same amount of money and quite reasonably end up with very different investment strategies.
Imagine two people each have $2 million.
One is 45, still working, earning a strong income and has no need to touch the money for many years.
The other is 68, retired, drawing regularly from the portfolio to fund their lifestyle.
The dollar amount is the same.
The investment problem is not.
The first person may have considerable capacity to tolerate short-term market falls because they have time and ongoing income on their side.
The second may need much more attention paid to liquidity, cash reserves and the order in which assets are sold.
That is why investment strategy should follow financial strategy, not lead it.
Before deciding what to invest in, we should first understand what the money needs to achieve.
Return is only one part of the answer
Investment markets encourage us to think in terms of performance.
What returned the most last year?
Which fund manager is currently number one?
Which market is about to outperform?
Which asset class should we buy now?
Those questions are not completely irrelevant. But none of them tells us whether a particular portfolio is appropriate for a particular person.
A portfolio producing 10 per cent a year is not automatically better than one producing 7 per cent.
The higher-returning portfolio may involve more volatility, less liquidity, more concentration or risks that the investor simply does not need to take.
The real question is not:
How much can we make?
It is:
What does the financial plan require this money to do?
That distinction matters enormously.
Sometimes the job is growth
For someone with a long investment horizon, part of the portfolio's job may be to grow faster than inflation and build wealth over decades.
Short-term volatility may matter relatively little.
The investor has time.
They may be making additional contributions.
They may not need to sell investments for many years.
In that situation, growth can legitimately be a major objective.
Sometimes the job is income
For someone in retirement, the portfolio may need to help fund regular spending.
But even here, we need to be careful with language.
The objective is not necessarily to maximise "income".
The objective is to fund the person's lifestyle.
There is an important difference.
Dividends, interest and distributions can all contribute to that objective, but so can the planned sale of assets.
The portfolio should serve the spending strategy, rather than the spending strategy being dictated by whatever income the portfolio happens to produce.
Sometimes the job is simply to be available
One of the least appreciated investment objectives is liquidity.
There are times when the most valuable characteristic of an investment is not its expected return.
It is the fact that the money can be accessed when needed.
A client might know they will need $150,000 within the next two years.
That money has a very different job from money that will not be needed for 20 years.
Putting both amounts into exactly the same investments simply because those investments offer higher expected returns would miss the point.
The time horizon attached to the money matters.
So does the consequence of being wrong.
Sometimes the job is to reduce uncertainty
This is where investing connects directly with what we describe at TUI as Financial Certainty.
Financial certainty does not mean knowing exactly what markets will do.
Nobody does.
It means constructing your financial affairs so that you do not need to know.
You have sufficient liquidity.
You are diversified.
You understand what the money is intended to fund.
You are not reliant on one investment, one asset class or one prediction being correct.
You have enough flexibility to adapt when circumstances change.
That is a very different objective from simply trying to achieve the highest possible return.
Risk looks different when you know the purpose
This also changes the way we think about risk.
Traditionally, investment risk is often described in terms of volatility.
How much might the value of the portfolio rise and fall?
Volatility matters, but it is only part of the story.
A much more useful question is:
What can stop this money from doing the job we need it to do?
That could be a permanent investment loss.
It could be insufficient liquidity.
It could be inflation.
It could be excessive concentration.
It could be being forced to sell investments at an unfortunate time.
It could even be the investor themselves abandoning a sensible strategy after markets fall.
Risk becomes much more meaningful when it is considered in the context of purpose.
The danger of investing without a purpose
Without a clear purpose, investors are easily drawn into the investment industry's favourite competition:
Who achieved the highest return?
That can lead to performance chasing.
Investments that have recently performed strongly receive more attention and more money.
Those that have lagged become unpopular.
Portfolios gradually become concentrated around yesterday's winners.
And investment decisions start being driven by markets rather than by the investor's actual financial needs.
The irony is that someone can make a series of apparently sophisticated investment decisions while moving further away from what they are actually trying to achieve.
Money is a tool
At TUI, we have long believed that money is a tool.
It is there to support life, not become the purpose of life.
That applies just as much to investing.
Every investment should have a reason for being there.
Some investments provide long-term growth.
Some provide diversification.
Some provide liquidity.
Some reduce dependence on other parts of the portfolio.
Some simply provide the confidence that money will be available when required.
None of those purposes is particularly exciting.
But good financial planning is not supposed to be exciting.
It is supposed to work.
So what is an investment actually for?
Ultimately, an investment should help make the life you want financially possible.
That is why we believe the investment conversation should not begin with:
"What should we buy?"
It should begin with:
"What does this money need to do?"
Once we know the answer to that, the investment decisions become much clearer.
Because the portfolio is not the objective.
Your life is.
Comments